Buying New Construction in DFW: Where the Real Leverage Is in 2027
I get asked this question almost daily: why will a builder negotiate on one lot but won't budge an inch on the house right next door? The answer has nothing to do with how well you negotiate or whether you brought the right agent. It comes down to how much of the builder's own money is already tied up in that specific house, how fast the surrounding community is selling, and where you land relative to their calendar year. A finished spec sitting on the market for sixty days is a completely different negotiation than a lot they control but haven't taken down yet. The builder's leverage shifts with every week that house sits, and your leverage shifts with it.
Most buyers walk into a model home thinking the incentive sheet is the deal. They see a number, whether that's a price cut, a rate buydown, closing costs covered, or upgrade dollars, and they assume the biggest number wins. That's not how it works. The biggest number on the incentive sheet isn't automatically the best deal for your specific situation, and there's a hard legal ceiling on how much a builder can actually contribute that has nothing to do with how well you negotiate. I've watched corner lot deals fall apart for reasons that had nothing to do with the house, the buyer, or the offer. If you're planning to buy new construction and want to know where the real leverage is before you sit down with a builder, here's what actually determines whether they can say yes.
Table of Contents
- What Actually Determines Whether a Builder Can Negotiate
- Why Finished Specs Give You More Leverage Than To-Be-Built Homes
- How Community Sales Velocity Changes What Builders Will Protect
- Why Builders Defend Their Base Price Instead of Just Cutting It
- The Real Trade-Offs Nobody Talks About with Builder Incentives
- Why Using the Builder's Preferred Lender Is Worth Comparing
- The Hard Legal Ceiling on Builder Contributions
- The One Thing You Actually Control at the Negotiating Table
- Which New Construction Strategy Is Right for You in 2027
- Conclusion
What Actually Determines Whether a Builder Can Negotiate
The builder's willingness to negotiate comes down to how much of their own money is already tied up in that specific house. A lot they control but haven't taken down yet costs them almost nothing to hold. They're paying land carry, but they haven't started construction, they haven't paid for materials, and they haven't committed labor. That lot is a placeholder. If you walk away, they lose nothing except the possibility of a sale. Compare that to a finished spec that's been sitting on the market for two months. That house has consumed their capital. They've paid for framing, plumbing, electrical, HVAC, flooring, countertops, appliances, and landscaping. Every week it sits is another week they're not getting that money back, and every week is another week they can't use that capital to start the next house.
The builder's overall year matters more than most buyers realize. If you're shopping in January and the builder had a strong fourth quarter, they're not desperate. They hit their numbers, their investors are happy, and they can afford to hold firm on price. If you're shopping in late November and they're still short of their annual goal, that same builder might be willing to move. Builders operate on fiscal calendars, and where you land relative to their year-end shapes what they're able to offer. I've seen builders who wouldn't budge in September suddenly offer aggressive incentives in December because they needed to close deals before the calendar flipped.
How fast the surrounding community is selling also changes what a builder is willing to protect. If homes in that neighborhood are going under contract within two weeks of hitting the market, the builder has no reason to negotiate. Demand is strong, inventory is moving, and they know another buyer is right behind you. If homes are sitting for sixty or ninety days, the builder knows they have a prcing problem or a perception problem, and they're more likely to work with you. Community sales velocity is one of the most reliable indicators of where you have leverage, and it's something you can research before you ever walk into the model home.
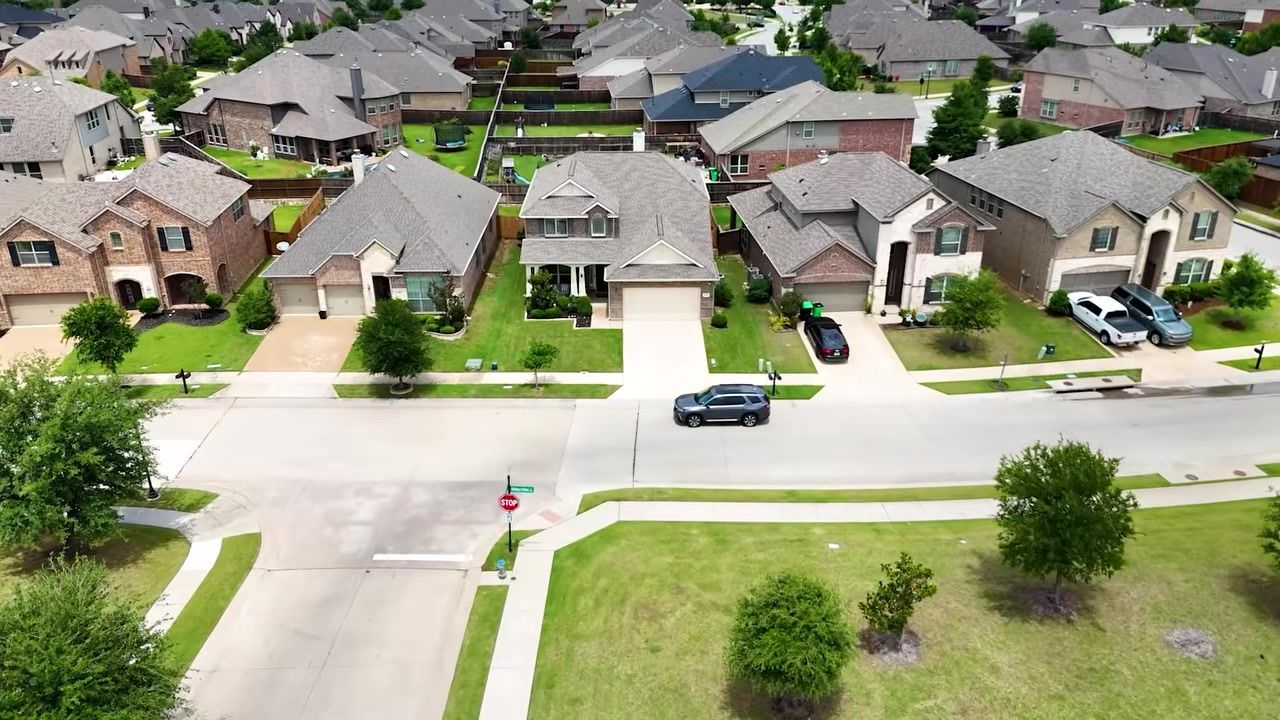
Why Finished Specs Give You More Leverage Than To-Be-Built Homes
A finished spec sitting on the market is the closest thing to a motivated seller you'll find in new construction. The builder has already spent the money. The house is done. It's not generating revenue, it's consuming capital, and every day it sits is another day the builder can't deploy that money into the next project. Finished specs also carry holding costs that to-be-built homes don't. The builder is paying property taxes on a completed structure, they're maintaining the landscaping, they're running the HVAC to keep the house climate-controlled, and they're keeping the lights on for showings. Those costs add up, and they create urgency.
To-be-built homes don't carry that same urgency. If you're buying a lot where construction hasn't started, the builder can afford to wait. They haven't committed the capital yet, and they're not bleeding money while the lot sits. The trade-off is that you're waiting six to nine months for the house to be built, and you're taking on the risk that the builder's incentives might change between now and closing. Finished specs let you close in thirty to forty-five days, and you're locking in the deal today. That speed and certainty come with leverage, especially if the spec has been sitting for more than a month.
I had a client looking at a corner lot spec that had been on the market for seventy days. The builder had already dropped the price once, and they were starting to get nervous. We came in with an offer that was lower than the list price but higher than what the builder would net if they dropped the price again and waited another sixty days. The builder accepted. That same builder wouldn't negotiate on a to-be-built lot in the same community because they didn't have money tied up in it yet. The difference wasn't the buyer or the offer. It was the builder's capital position on that specific house.
How Community Sales Velocity Changes What Builders Will Protect
Builders don't just look at one house in isolation. They're looking at the entire community and how fast it's moving. If a neighborhood is selling three or four homes a month and the builder only has six lots left, they're not going to negotiate. Scarcity creates urgency, and the builder knows they can hold firm on price because demand is outpacing supply. If that same neighborhood is selling one home a month and the builder has twenty lots left, they know they have a problem. Either the price is too high, the product isn't resonating, or the location isn't as desirable as they thought. That's when they start offering incentives.
Community sales velocity also tells you whether the builder is willing to protect their base price. If homes are moving quickly, the builder will defend that base price aggressively because dropping it sends a signal to every other buyer in the community that they overpaid. Builders would rather offer incentives, rate buydowns, or upgrade credits than cut the base price, because those concessions don't show up on the appraisal and they don't create comp problems for future sales. If the community is slow, the builder might be willing to adjust the base price, but only if they're confident it won't tank the value of the homes they've already sold.
You can research sales velocity before you ever talk to the builder. Look at how many homes have closed in the past six months, how many are under contract, and how many are still available. If the builder has been sitting on the same ten lots for a year, you have leverage. If they've sold fifteen lots in the past three months, you don't.
Why Builders Defend Their Base Price Instead of Just Cutting It
Builders will do almost anything to avoid cutting the base price. The reason is simple: every home they sell sets a comp for the next home. If they drop the base price by twenty thousand dollars, that lower price shows up on the appraisal for every future buyer in that community. It also creates a perception problem with buyers who already closed. Those buyers see the new price and feel like they overpaid, and that erodes trust. Builders would rather offer fifty thousand dollars in incentives than drop the base price by twenty thousand, because the incentives don't show up on the appraisal and they don't create comp issues.
This is why you'll see builders offer rate buydowns, closing cost credits, and upgrade allowances instead of price cuts. A rate buydown might cost the builder thirty thousand dollars, but it doesn't lower the sales price. The appraisal still comes in at the original base price, and the builder protects the value of every other home in the community. For you as the buyer, the trade-off is whether you'd rather have a lower purchase price or a lower monthly payment. If you're planning to refinance in two years, the rate buydown might not matter. If you're planning to stay in the house for ten years, the lower payment might save you more than a price cut would have.
The other reason builders defend their base price is that it protects their margin. Builders operate on thin margins, especially in competitive markets. If they start cutting prices, they risk going underwater on the project. Incentives let them move inventory without destroying their margin, because they can structure the incentive in a way that costs them less than a straight price cut. A ten-thousand-dollar upgrade allowance might only cost the builder six thousand dollars in actual material and labor costs, but it feels like a bigger concession to the buyer.
The Real Trade-Offs Nobody Talks About with Builder Incentives
The biggest number on the incentive sheet isn't automatically the best deal for your specific situation. I've seen buyers take a fifty-thousand-dollar rate buydown when they would have been better off with a twenty-thousand-dollar price cut, and I've seen buyers take upgrade credits they didn't need because the number looked impressive. The question you need to ask is what the incentive actually does for you, not what it costs the builder.
A rate buydown only matters if you're keeping the loan long enough to recoup the cost. If you're planning to refinance in eighteen months, the builder is paying to buy down a rate you're not going to keep. A price cut lowers your loan amount, which lowers your monthly payment and your equity position from day one. Closing cost credits help if you're cash-constrained, but they don't lower your purchase price or your monthly payment. Upgrade credits let you customize the house, but they don't reduce your loan balance. The best incentive is the one that aligns with your actual plan for the house.
The other trade-off nobody talks about is that some incentives are contingent on using the builder's preferred lender. If you refuse to use the builder's lender on principle, you might be walking away from ten or twenty thousand dollars in incentives. I'm not saying you should always use the builder's lender, but you should at least compare. Get a quote from the builder's lender and a quote from your own lender, and see which one actually costs you less over the life of the loan. Sometimes the builder's lender is more expensive even with the incentive. Sometimes they're cheaper. You won't know until you run the numbers.
Why Using the Builder's Preferred Lender Is Worth Comparing
Most buyers assume the builder's preferred lender is a bad deal. They think the builder is getting a kickback, the rates are inflated, and they're better off using their own lender. Sometimes that's true. Sometimes it's not. The builder's preferred lender often has access to incentives that outside lenders don't, and those incentives can offset a slightly higher rate or slightly higher fees. The builder might offer an additional ten thousand dollars in closing costs if you use their lender, or they might offer a rate buydown that only applies if you finance through their preferred partner.
The reason builders push their preferred lender is that it makes the transaction smoother. The builder's lender knows the builder's process, they know the timelines, they know the appraisal requirements, and they know how to close on time. An outside lender might be cheaper on paper, but if they delay the closing by two weeks because they don't understand the builder's requirements, you've just cost yourself two weeks of rent or two weeks of overlap on your current mortgage. Speed and certainty have value, and sometimes that value is worth paying for.
The smart move is to get quotes from both lenders and compare the total cost over the period you plan to keep the loan. If you're planning to refinance in two years, compare the total payments over two years plus the closing costs. If you're planning to keep the loan for ten years, compare the total payments over ten years. Don't just look at the rate. Look at the fees, the incentives, and the total cost. I've seen buyers save fifteen thousand dollars by using the builder's lender, and I've seen buyers save ten thousand dollars by using their own lender. It depends on the deal.
The Hard Legal Ceiling on Builder Contributions
There's a hard legal ceiling on how much a builder can actually contribute, and it has nothing to do with how well you negotiate. Lenders cap seller concessions at a percentage of the purchase price, and that cap varies depending on your loan type and your down payment. For a conventional loan with less than ten percent down, the cap is three percent. For a conventional loan with ten to twenty-five percent down, the cap is six percent. For an FHA loan, the cap is six percent. For a VA loan, the cap is four percent. If the builder offers you more than the lender allows, the excess doesn't help you. It just gets wasted.
This is why you'll sometimes see builders offer a price cut instead of additional closing costs. If you're already at the concession cap and the builder wants to give you more, they have to lower the purchase price because the lender won't let them contribute any more toward your closing costs. The cap also explains why builders structure incentives the way they do. A rate buydown doesn't count toward the concession cap because it's not a direct payment to you. An upgrade credit doesn't count toward the cap because it's not a closing cost. The builder is working within the lender's rules, and those rules limit what they can offer.
The other thing buyers don't realize is that the concession cap is based on the purchase price, not the appraised value. If you negotiate a ten-thousand-dollar price cut, the concession cap drops because the purchase price dropped. That ten-thousand-dollar price cut might cost you three hundred dollars in allowable concessions, which means you're only netting ninety-seven hundred dollars in actual savings. The math gets complicated, and it's why you need to run the numbers with your lender before you agree to any deal.
The One Thing You Actually Control at the Negotiating Table
The one thing you actually control at the negotiating table has nothing to do with the builder at all. It's your willingness to walk away. Builders know when you're bluffing, and they know when you're serious. If you're emotionally attached to the house, if you've already told the sales agent this is your dream home, if you've brought your family back three times to look at the model, the builder knows you're not walking away. You have no leverage. If you're willing to walk away, if you've made it clear you're looking at three other communities, if you're not in a hurry, the builder knows they have to compete for your business.
The other thing you control is your timeline. If you need to close in thirty days, you have less leverage than someone who can wait six months. Builders know urgency when they see it, and they know they don't have to negotiate as hard if you're desperate. If you can afford to wait, you can afford to negotiate. If you can't afford to wait, you're taking whatever deal the builder offers.
I had a client looking at a corner lot that checked every box. Great location, great floor plan, great price. We made an offer, and the builder came back with a counteroffer that was barely different from their original ask. My client wanted to accept it because he was afraid someone else would buy the lot. I told him to walk away. We found another lot in a different community, made an offer, and the builder accepted it immediately. Two weeks later, the first builder called and said they'd accept our original offer. The lot was still available, and they realized my client wasn't bluffing. We ended up going with the second community because the deal was better, but the point is that walking away gave us leverage we didn't have when we were emotionally attached to the first lot.
Which New Construction Strategy Is Right for You in 2027
If you're looking for the most leverage, focus on finished specs that have been sitting on the market for more than thirty days. Those homes give you the most negotiating power because the builder has already spent the money and they're paying holding costs every day the house sits. You'll close faster, you'll lock in the deal today, and you'll avoid the risk that the builder's incentives change between now and closing. The trade-off is that you're buying what the builder already built, and you don't get to customize the finishes or the floor plan.
If you want to customize the house and you're not in a hurry, look for communities where sales velocity is slow. If the builder has been sitting on the same lots for six months and they're only selling one or two homes a month, they're more likely to negotiate. You'll wait longer for the house to be built, but you'll get the floor plan and finishes you want, and you'll have more leverage at the negotiating table because the builder knows they need to move inventory.
If you're planning to refinance in the next two years, prioritize a lower purchase price over a rate buydown. The rate buydown only helps you if you keep the loan long enough to recoup the cost, and if you're refinancing in eighteen months, you're not keeping the loan long enough. A lower purchase price reduces your loan balance, which reduces your monthly payment and improves your equity position from day one. If you're planning to stay in the house for ten years and you're not planning to refinance, a rate buydown might save you more than a price cut would have.
Conclusion
The leverage in a new construction deal comes down to how much of the builder's own money is already tied up in that specific house, how fast the surrounding community is selling, and where you land relative to their calendar year. A finished spec sitting on the market for sixty days is a completely different negotiation than a lot they control but haven't taken down yet. The biggest number on the incentive sheet isn't automatically the best deal for your specific situation, and there's a hard legal ceiling on how much a builder can actually contribute that has nothing to do with how well you negotiate. The one thing you actually control at the negotiating table is your willingness to walk away, and that's the most powerful leverage you have.
If you're planning to buy new construction in DFW and you want to know where the real leverage is before you sit down with a builder, let's talk. Call or text me at 469-707-9077 or book a FREE consultation here and I'll tell you where I think the leverage is on that deal. We'll walk through your specific situation and figure out which strategy gives you the most negotiating power. I'm here to help you walk in knowing what you can actually ask for.
FAQ: Buying New Construction in 2027
How much can a builder actually negotiate on price?
It depends on how much of their own money is already tied up in that specific house. A finished spec that's been sitting on the market for sixty days gives you more leverage than a lot they haven't taken down yet. Builders will defend their base price aggressively because every home they sell sets a comp for the next home, so they'd rather offer incentives than cut the price. The amount they can negotiate also depends on how fast the surrounding community is selling and where you land relative to their calendar year.
Should I use the builder's preferred lender?
You should at least compare. The builder's preferred lender often has access to incentives that outside lenders don't, and those incentives can offset a slightly higher rate or slightly higher fees. Get a quote from the builder's lender and a quote from your own lender, and compare the total cost over the period you plan to keep the loan. Sometimes the builder's lender is cheaper even with a slightly higher rate, and sometimes your own lender is cheaper even without the incentives. You won't know until you run the numbers.
What's the difference between a rate buydown and a price cut?
A rate buydown lowers your interest rate, which lowers your monthly payment, but it doesn't reduce your loan balance. A price cut lowers your purchase price, which lowers your loan balance and your monthly payment. If you're planning to refinance in the next two years, a price cut is usually better because you're not keeping the loan long enough to recoup the cost of the rate buydown. If you're planning to stay in the house for ten years and you're not planning to refinance, a rate buydown might save you more.
How do I know if a community is selling fast or slow?
Look at how many homes have closed in the past six months, how many are under contract, and how many are still available. If the builder has been sitting on the same ten lots for a year, the community is slow and you have leverage. If they've sold fifteen lots in the past three months, the community is fast and you don't have much leverage. You can also ask the sales agent how many homes they've sold in the past ninety days, but verify that number with public records because sales agents sometimes inflate the numbers.
What's the legal limit on builder contributions?
Lenders cap seller concessions at a percentage of the purchase price, and that cap varies depending on your loan type and your down payment. For a conventional loan with less than ten percent down, the cap is three percent. For a conventional loan with ten to twenty-five percent down, the cap is six percent. For an FHA loan, the cap is six percent. For a VA loan, the cap is four percent. If the builder offers you more than the lender allows, the excess doesn't help you.
When is the best time of year to negotiate with a builder?
Late November and December are usually the best months because builders are trying to hit their annual sales goals before the calendar flips. If they're short of their target, they're more likely to offer aggressive incentives to close deals before year-end. January and February are usually the worst months because builders just hit their numbers and they're not desperate. The builder's fiscal calendar matters more than the actual season, so ask when their fiscal year ends and try to shop during the last quarter of their year.
Zak Schmidt
From in-depth property tours and builder reviews to practical how-to guides and community insights, I make navigating the real estate process easy and enjoyable.